Practice related questions (6)Progress & bookmarks
Current section
1-2-2 Implementation Procedure of System Audits
p. 380
Practice this section 6 linked exam questions with default filters
Progress
Not marked complete
p. 380 · PDF 387
1-2-2 Implementation Procedure of System Audits
The following is the implementation procedure of system audits based on the “System Audit Standards.” In order to effectively and efficiently conduct a system audit, it is necessary to make implementation preparation for obtaining support and active cooperation of the subject to be audited before the audit is conducted.
p. 381 · PDF 388
View original source box · p. 381
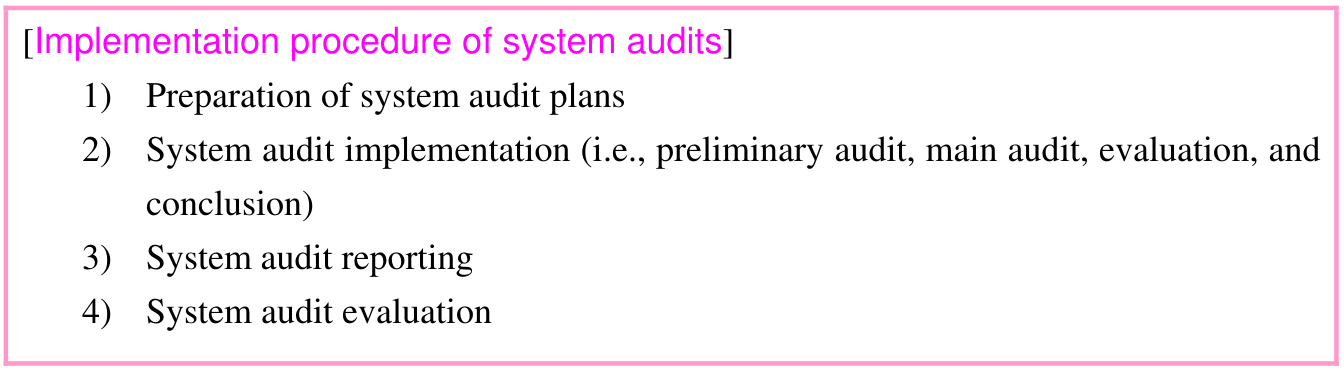
Four numbered stages appear in source order: preparation of system audit plans; system audit implementation, including preliminary audit, main audit, evaluation and conclusion; system audit reporting; system audit evaluation.
(1) Preparation of system audit plans
In the preparation of system audit plans, in order to effectively and efficiently achieve the purpose of system audits to be conducted, the system auditor prepares appropriate system audit plans concerning contents, timing, and scope of audit procedure, and documents them as the system audit plans. The following three plans are prepared as system audit plans.
View original source box · p. 381
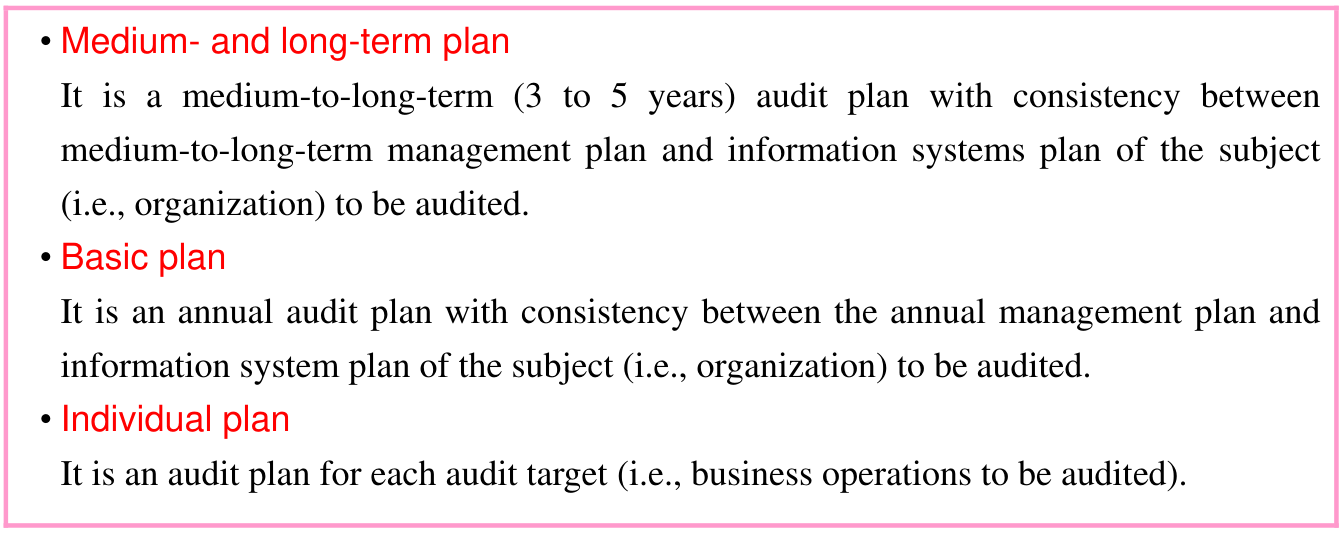
The bordered list describes a medium- and long-term plan of 3 to 5 years, an annual basic plan, and an individual plan for each audit target.
It is ideal to prepare the system audit plans in the sequence of a medium- and long-term plan, a basic plan, and an individual plan. However, for practical purposes, most of the time the basic plan is prepared first, and then the medium- and long-term plan is prepared by consolidating the basic plans of several years. After that, the individual plan is prepared by defining the basic plan in detail for each audit target. In the preparation of system audit plans, on the basis of the results (e.g., frequency of risk occurrence, extent of impact) of risk assessment related to information systems, audit targets and important audit topics are selected. After that, audit scope and audit procedures are defined, and the corresponding audit implementation framework and audit schedule are decided. The system audit plans that are prepared in this manner are released after the approval is obtained from the head of the organization of the department to be audited. However, in the event that the fulfillment of audit purpose possibly may be blocked (e.g., “New facts are
p. 382 · PDF 389
found during the audit process,” “Environment of the subject to be audited has changed”), flexible operation is required so that the plans can be modified on a case-by-case basis such as by changing the audit procedure.
Section progress
Original chapter exercises
Original chapter exercises →New FE Textbook Vol.2 · First Edition, April 2015